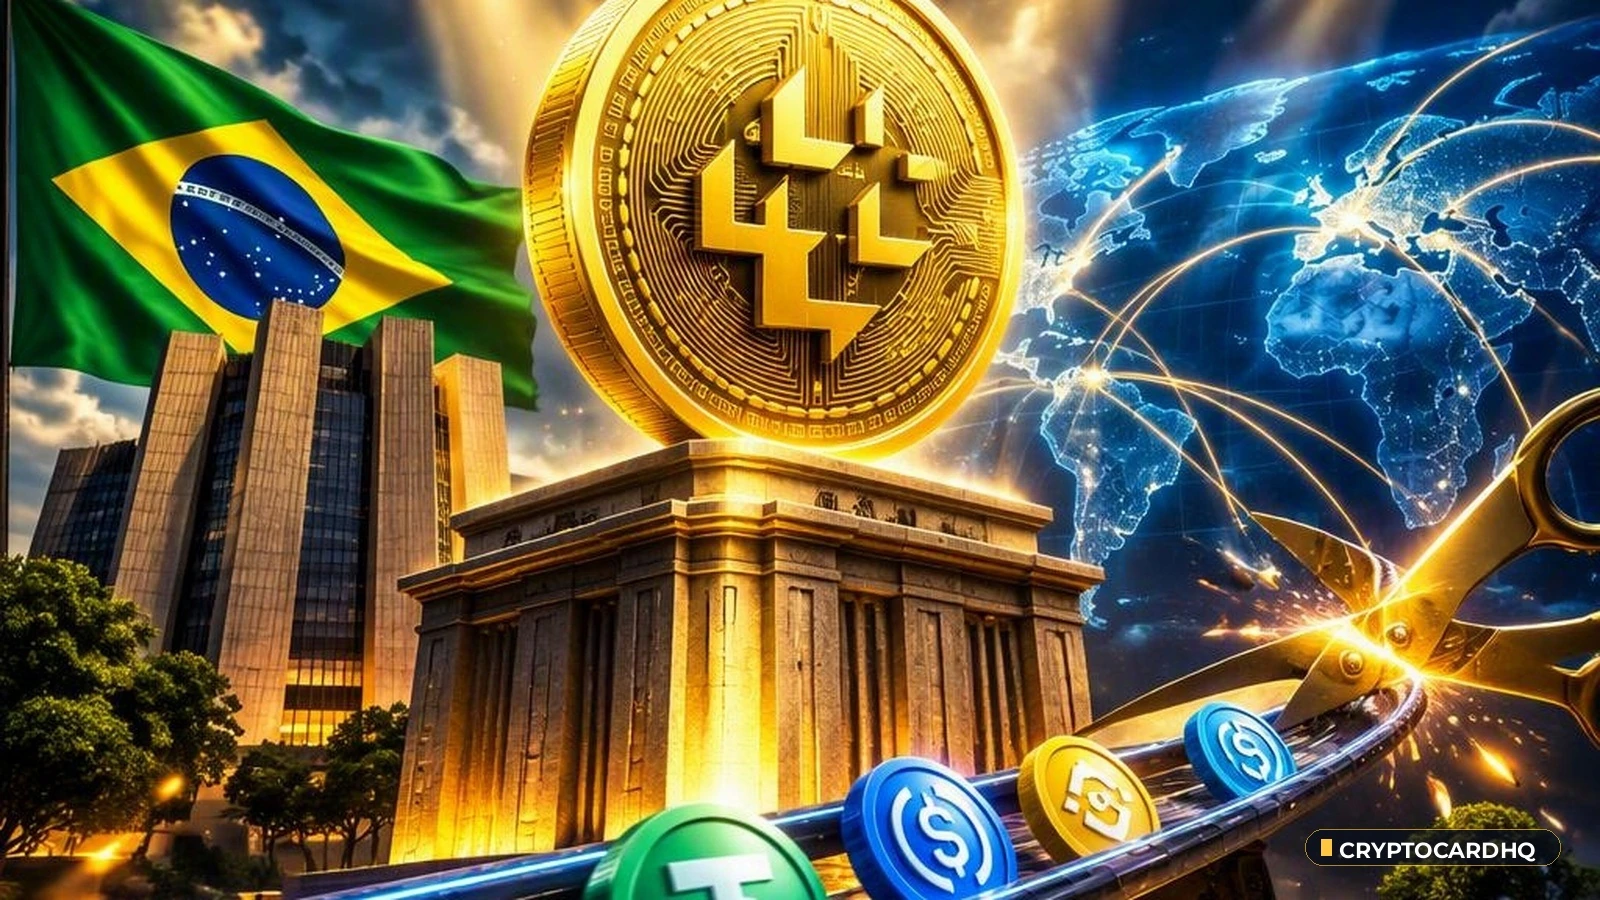
In a decisive regulatory intervention reshaping Latin America's primary digital asset market, the Central Bank of Brazil (Banco Central do Brasil) has shut down a major cross-border liquidity channel. Under the provisions of Resolution 561, the central bank has prohibited licensed foreign exchange (FX) institutions from using stablecoins and virtual assets to clear international transactions with overseas counterparties. This policy change directly alters how institutional payment processors, corporate treasury desks, and cross-border settlement rails interact with Brazilian financial infrastructure.
Key Takeaways
- Resolution 561 Mandate: The Central Bank of Brazil officially bars virtual assets and stablecoins from settling cross-border payment flows between domestic regulated FX providers and foreign counterparties.
- Enforcement Deadline: Mandatory compliance takes effect on October 1, giving financial institutions and payment gateways a narrow runway to overhaul institutional settlement pipelines.
- Strict Settlement Alternatives: Cross-border wholesale clearing legs must now route strictly through traditional licensed FX contracts or qualifying non-resident Brazilian Real accounts.
- Market Scope: The intervention targets institutional clearing routes across Brazil's massive $1.1 trillion total financial flow ecosystem, preventing dollar-pegged stablecoins from functioning as an informal FX clearing bridge.
Market Snapshot at Time of Reporting: At the time of reporting, BTC ($81,266.00, +3.93% 24h | Range: $77,972.30 - $81,741.00), while SOL ($112.01, +5.16% 24h | Range: $105.36 - $114.32).
Resolution 561: Closing the Stablecoin FX Arbitrage Channel
Brazil's central bank introduced Resolution 561 to eliminate the practice of using digital tokens as off-book bridge instruments between domestic authorized FX dealers and offshore counterparties, as reported by CryptoSlate. Under the incoming rulebook, any settlement leg linking a regulated Brazilian FX broker to a foreign partner can no longer replace sovereign currency legs with dollar-backed tokens such as USDT or USDC.
Starting October 1, cross-border flows must settle through two specific rails: authorized foreign exchange contracts executed directly within central bank reporting systems, or qualifying non-resident accounts denominated in Brazilian Real. By removing digital assets from the wholesale inter-firm settlement leg, monetary authorities intend to restore comprehensive supervisory oversight over cross-border capital velocity.
Historically, institutional payment gateways, corporate treasuries, and regional fintech networks adopted stablecoins to sidestep correspondent banking delays, cut administrative documentation burdens, and avoid steep bank spreads. Resolution 561 re-establishes regulatory controls over the domestic FX boundary, mandating that every institutional cross-border transfer generates an audited foreign exchange record within the central bank's surveillance systems.
Market Context: Reining In Latin America's Leading Crypto Corridor
Brazil is Latin America's most liquid digital asset ecosystem, processing heavy transaction volumes in dollar-denominated tokens. A growing share of import-export invoicing, fintech cross-border transfers, and B2B corporate trade migrated to blockchain rails over the past several years. This growth closely mirrors the structural dynamics outlined in CryptoCardHQ's analysis of stablecoins and the global payments shift, where tokenized dollars rapidly challenged traditional correspondent networks in high-volume emerging markets.
Central banks monitor unmonitored digital capital corridors closely due to risks concerning foreign reserve tracking, anti-money laundering controls, and exchange-tax enforcement. When domestic FX brokers settle overseas balances via private wallets, transactions bypass traditional interbank reporting books. Across Brazil's broader foreign exchange and trade flow market—representing over $1.1 trillion in total gross volume—regulators decided to draw clear operational boundaries before alternative digital rails became an entrenched parallel settlement system.
Fintech operators providing rapid settlement between Brazilian merchants and Asian or North American suppliers now face immediate restructuring demands. The practice of netting cross-border balances using stablecoin inventories across foreign liquidity hubs terminates at the licensed institution level on October 1.
Key Figures & Operational Breakdown
The table below contrasts the regulatory landscape preceding Resolution 561 with the incoming compliance requirements:
| Operational Factor | Prior Framework | Resolution 561 Mandate | Strategic Impact |
|---|---|---|---|
| Wholesale Cross-Border Settlement | Stablecoins permitted across inter-firm FX counterparties | Strictly prohibited for regulated FX providers | Eliminates unregulated stablecoin bridging for licensed brokers |
| Authorized Settlement Conduits | Private wallet transfers or offshore crypto exchange custody | Licensed FX transactions or qualifying non-resident BRL accounts | Mandates formal FX contracts logged directly with the central bank |
| Enforcement Date | Flexible operational transition | Strict enforcement begins October 1 | Imposes immediate migration pressure on treasury architectures |
| FX Capital Tracking | Asynchronous commercial records and voluntary declarations | Real-time regulatory transparency into capital flows | Restricts corporate tax avoidance and unregulated shadow FX arbitrage |
| B2B Clearing Velocity | Continuous 24/7 on-chain settlement finality | Tied to banking-hour FX processing schedules | Lengthens clearance windows and reintroduces standard bank spreads |
Strategic Risks and Compliance Headwinds
The primary friction from Resolution 561 centers on cross-border merchant aggregators and fintech payment networks. Processors that built hybrid architectures—accepting retail payments through Brazil's Pix network and clearing the foreign outbound leg using stablecoins—must phase out these workflows before October 1.
Conducting licensed foreign exchange operations in Brazil will now demand direct currency matching through formal FX contracts. This requirement reintroduces administrative registration expenses, statutory IOF exchange taxes, and intermediary bank fees. As documented in market reviews like Circle's acquisition of Tazapay to contest global payment rails, fintech infrastructure providers built competitive advantages on narrow margins by avoiding banking friction; Brazil's ruling restores those traditional compliance hurdles.
Liquidity fragmentation presents an acute short-term operational hazard. Digital asset liquidity providers running B2B off-ramps in São Paulo and Rio de Janeiro must audit counterparty workflows immediately. Any domestic FX intermediary clearing trade obligations via tokens must be isolated or restructured to avoid abrupt settlement freezes, rejected transfers, and liquidity disconnects as the deadline hits.
Practical Takeaways for Crypto Cardholders and Everyday Users
For retail consumers and crypto debit card users, Resolution 561 focuses on the institutional plumbing rather than self-custody wallets or direct exchange accounts. Individuals retain the legal right to purchase, hold, and transact with virtual assets on registered exchanges. Downstream consumer card products, however, will see practical changes:
- 1Prepaid Card Reloads and Liquidity: Users managing multi-currency accounts or funding crypto cards can review our Best Crypto Cards guide to evaluate how different card programs structure domestic conversions. While consumer card spending remains fully legal, cards depending on back-end stablecoin liquidation to fund local real balances may face wider foreign exchange spreads or revised processing costs.
- 2Cross-Border E-Commerce Processing: International digital storefronts selling to Brazilian consumers through regional payment aggregators may experience longer settlement cycles, higher checkout surcharges, or altered processing paths.
- 3Tracking Card Infrastructure Updates: As domestic regulatory environments adjust across emerging economies, reading the Crypto Cards News category helps spenders identify which global payment card issuers maintain resilient, fully compliant banking integrations without lowering cardholder spending limits.
Cardholders should check whether their digital wallet platforms and neobanks rely on licensed FX intermediaries that have already transitioned to compliant non-resident accounts ahead of October 1.
Catalysts & What to Watch Next
- October 1 Hard Deadline: The central bank cut-off requiring all licensed FX brokers to halt virtual asset settlement with foreign partners.
- Payment Gateway Architecture Overhauls: Formal announcements from cross-border payment processors regarding alternative banking channels on the Brazil-US and Brazil-Asia trade corridors.
- Central Bank Circulars on Non-Resident Accounts: Further technical criteria clarifying documentation rules and qualification thresholds for offshore accounts holding Brazilian Real.
- Growth of Real-Pegged Onshore Tokens: Monitoring whether locally issued, BRL-backed stablecoins gain traction as dollar-pegged foreign tokens exit regulated institutional pipelines.